

Money App - Cash Advance
by PRG Ventures.
4.2
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.2
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
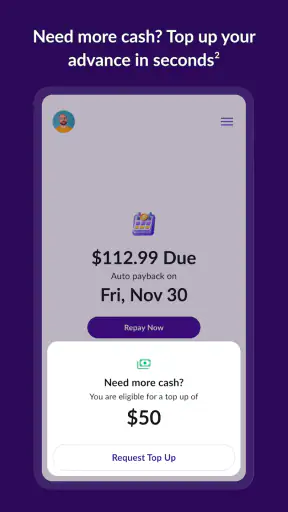
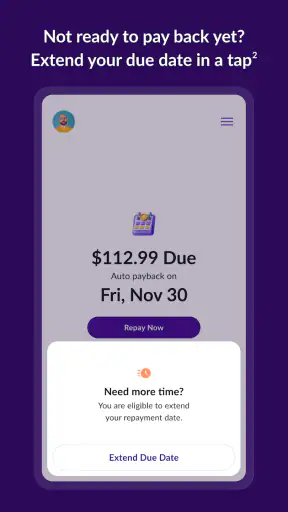
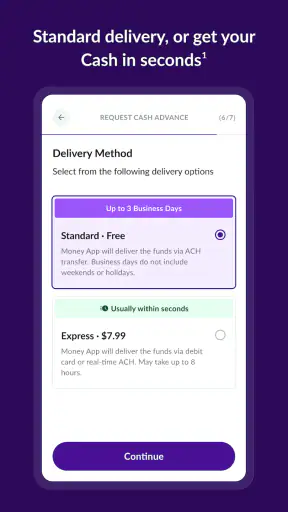
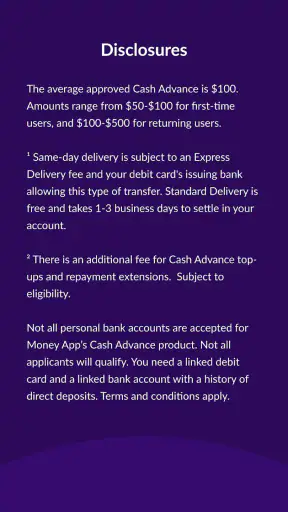
 Analysis by Getfullapps
I approached Money App - Cash Advance as a finance tool for a very specific moment: when an unexpected bill arrives and I need to understand whether an emergency-cash option is worth exploring. Its central promise is simple, but financial apps deserve a more careful look than a quick tap on a download button. The important question is not only whether the app is easy to open; it is whether I can read the information comfortably, move through the process without confusion, and make a sensible decision before accepting any financial commitment.
Developed by PRG Ventures, this free app sits in the finance category and is intended for Everyone. It has attracted more than half a million installs, with an average rating of 4.2 from roughly ten thousand ratings and about two thousand reviews. Those figures suggest that many people find it useful, although they should not replace my own reading of the terms or my judgment about borrowing.
How Money App - Cash Advance feels to use in real situations
I focus on what the app’s narrow emergency-cash purpose changes in an ordinary moment: it gives me a place to investigate an option without turning the search into a full budgeting session. That convenience is most useful when I can stay deliberate, so I’ll look at how to separate browsing from a borrowing decision and what to weigh before moving ahead.
Readability and navigation when money is already stressful
The strongest part of the experience is its focused purpose. I do not open it expecting budgeting lessons, investment charts, or a full banking replacement. I open it because I want to investigate emergency cash. That narrow focus can make the first decision easier: I can concentrate on the information connected to the request instead of wandering through unrelated financial tools.
That simplicity matters when someone is dealing with a late utility payment, a medical expense, or a repair that cannot wait. In those situations, attention is limited. A finance app that forces me to interpret too many sections at once can create more pressure than help. Money App - Cash Advance is more approachable when I treat it as an information and application pathway rather than as a complete financial command center.
I would still slow down at every screen involving eligibility, repayment, fees, or authorization. Emergency-cash products can look straightforward at the beginning and become more consequential later. My practical habit is to read each amount and date before moving forward, then pause if a button uses vague language. A clean route through an app is useful, but clean navigation should never be confused with a favorable borrowing decision.
The app’s store presence identifies it simply as “Money App,” while its cash-advance purpose is clearer in the full product name. That distinction is worth remembering when searching for it, especially because finance apps can have similar names. Once installed, I would verify that the developer shown is PRG Ventures before entering personal information.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
For readers who prefer large text or who tire quickly while reading dense financial explanations, the best approach is to use the phone’s own display settings where available and review one screen at a time. I would avoid increasing the pace just because the app appears uncomplicated. The most important content in a cash-advance flow is often the small explanatory text, not the prominent action button.
Motor and sensory considerations
Money App - Cash Advance is easier to approach for people who can use standard touch controls and read ordinary mobile text without assistance. I would not describe it as a specialist accessibility product, and I would not assume that every user will experience the same level of comfort. A person with limited dexterity may need larger system controls, more time between taps, or help from a trusted person when entering details.
That is particularly important in a financial application because an accidental tap can have more serious consequences than a mistaken selection in a casual game. I prefer to keep my phone steady, use deliberate taps, and check the next screen rather than rapidly pressing through the process. If a user relies on voice control, screen magnification, a screen reader, or alternative input, the sensible first step is to test whether the phone’s built-in assistance works consistently across the screens before attempting a real request.
People with visual sensitivities may also want to use the app in a calm environment and adjust brightness or contrast through the device. I would not make assumptions about color-based warnings or visual emphasis without checking each screen personally. If an important distinction is communicated mainly through color, that can be difficult for some users, so reading the surrounding wording is safer than relying on appearance alone.
For users with hearing loss, a finance workflow is generally more comfortable when essential information is presented in text rather than depending on sound. I would keep notifications visible and review written messages inside the app or on the device. For users with cognitive or memory-related difficulties, writing down the requested amount, the repayment obligation, and any relevant dates before confirming can reduce the chance of forgetting what was agreed.
One useful accommodation is to involve another person without handing over control of the account. A trusted friend can read the screen aloud or help compare the figures while the account holder makes the final decision. That approach preserves personal oversight and is safer than sharing passwords or allowing someone else to complete an unfamiliar financial action independently.
Situational access: when the app helps and when it does not
The most realistic use case is a short-term cash gap that is genuinely understood. Imagine a household facing a necessary appliance repair just before payday. I could use the app to explore whether an emergency-cash option may fit, but I would first calculate what remains after rent, food, transport, and existing obligations. The app can support the search for a solution; it cannot make the underlying shortage affordable.
That distinction separates a useful emergency tool from a dangerous habit. If the same gap appears every month, a cash advance is unlikely to solve the real problem. In that situation, I would compare it with speaking to a bank, contacting the bill provider about a payment arrangement, checking whether an employer offers an advance, or seeking advice from a nonprofit financial counselor. A slower option may be better if it avoids repeating short-term borrowing.
The app can also be practical for someone who wants a mobile-first process and dislikes visiting a branch. A phone-based route may be easier for people who work irregular hours, live far from financial services, or have difficulty arranging transportation. It may be less comfortable for someone who wants a human explanation before sharing details. For that person, a local bank or credit union may offer more reassurance, even if the process takes longer.
Language and comprehension are part of situational access too. I would not continue if I could not understand the financial wording well enough to explain the obligation back to someone else. Translation tools can help with general reading, but they should not be treated as a substitute for understanding legally or financially important terms. If a user needs information in another language, a provider that offers clear human support in that language may be a better choice.
Device conditions can change the experience. A person using an older phone may have less comfortable text rendering or slower transitions than someone with a newer device. The app supports Android 7.0 and later, which makes it available to many older Android users, but compatibility alone does not guarantee that every screen will be equally comfortable on every handset. I would update the device where possible, use a reliable connection, and avoid beginning a time-sensitive request when the battery is nearly empty.
Three practical habits that improve the experience
My first habit is to separate exploration from commitment. I would open the app when I have enough time to read, note the amount I am considering, and identify the point at which the app asks me to accept or authorize something. If I am rushed, distracted, or emotionally upset, I would stop before that point and return later. This simple boundary prevents an urgent situation from turning into an automatic decision.
My second habit is to create a written comparison before choosing. I would place the possible cash advance beside alternatives such as delaying a nonessential purchase, negotiating a bill, borrowing from a trusted person, or using an existing account feature. The comparison should include the total amount to repay and the date it would leave my budget, not merely the amount that arrives. This is more revealing than judging the offer by its headline amount.
My third habit is to preserve a record of what I accepted. I would save or write down the relevant confirmation details, repayment information, and support instructions shown during the process. That record is valuable for people with memory difficulties, users who need to review information with an adviser, and anyone who later needs to compare the transaction with a bank statement. It also reduces dependence on remembering a stressful conversation or screen.
A fourth habit is to protect privacy during assisted use. If someone helps me because of a visual, motor, or reading difficulty, I would let them explain the content without giving them unnecessary access to passwords, security codes, or unrelated financial accounts. Accessibility should not require sacrificing control of sensitive information.
Remaining barriers and where another option may win
The largest barrier is not the act of opening a finance app; it is the risk of making a fast borrowing decision under pressure. A polished mobile flow can make an emergency option feel more certain than it really is. I would therefore judge the app by how well I understand the obligation, not by how quickly I reach the next screen.
Another limitation is that a focused cash-advance app is not the same as a complete money-management service. Someone looking for spending categories, long-term savings goals, credit education, or detailed account aggregation may be better served by a budgeting app or their regular bank. Money App - Cash Advance makes more sense when the immediate question is whether emergency cash is available, not when the goal is to rebuild an entire financial plan.
I would also skip it if I needed guaranteed personal guidance, face-to-face support, or a clearly explained alternative to borrowing. A bank representative, credit counselor, or community financial service may be more appropriate when the situation involves several debts, uncertain income, or a recurring inability to meet essential expenses. The app may help start a search, but it should not be the only source of advice in a complicated case.
Users should be especially cautious if they have difficulty tracking dates or maintaining enough money for a future repayment. In that case, the convenience of receiving emergency cash may be outweighed by the risk of another shortfall. I would not use any cash-advance service to cover a previous advance, and I would not proceed simply because I had already spent time completing the application.
There is also a human-factors issue for people with low digital confidence. Even when the route feels simple, unfamiliar financial language can create uncertainty. I would recommend reading the screen aloud, taking screenshots only when they do not expose sensitive information, and asking a trusted adviser to explain the figures. If the user cannot state the repayment responsibility in plain language, the process is not ready to continue.
Updates, suitability, and everyday expectations
The app was released on February 12, 2024, and its current version is 2.47.0. For me, that makes checking the installed version worthwhile before relying on it during an emergency. Updates can change navigation or wording, so I would not assume that a screen remembered from an earlier session looks identical later. I would also keep the phone’s operating system in a supported condition rather than treating an old installation as permanent.
Its free price lowers the barrier to trying the app, but “free” should not be interpreted as “free money.” The financial consequences depend on the specific offer and the user’s ability to repay it. I would regard the download cost as separate from the cost of any financial product presented inside the experience. That is one of the most important distinctions for a first-time user.
The Everyone age classification makes the app broadly approachable from a content perspective, but age suitability does not remove the need for financial maturity. A younger user, or anyone unfamiliar with borrowing, should involve a responsible adult or qualified adviser before accepting an obligation. The rating and install figures show that the app has a substantial audience, yet popularity alone cannot tell me whether it fits my budget or my accessibility needs.
Compared with a traditional bank, the app may feel more direct and less tied to branch hours. Compared with a budgeting tool, it is more focused on an immediate cash need and less suited to long-term planning. Compared with informal borrowing from family or friends, it offers a more structured digital route but may provide less personal flexibility. Each alternative solves a different problem, so I would choose based on the situation rather than convenience alone.
My inclusive verdict
I see Money App - Cash Advance as a potentially useful starting point for someone who needs to investigate emergency cash from a phone and can carefully read and evaluate the financial terms. Its focused purpose, free entry point, Android compatibility from version 7.0 onward, and broad audience make it approachable for many people. I especially appreciate that it can fit situations where visiting a branch is difficult or where a user wants to explore an option privately.
My recommendation comes with a firm condition: use it as a decision-making aid, not as a substitute for a budget or financial advice. People with visual, motor, hearing, language, or cognitive needs should test the experience with their device settings and use trusted assistance without surrendering account control. If the text is hard to understand, the repayment schedule does not fit, or the emergency is part of a repeating pattern, another route is likely safer.
The best reason to try this app is convenience during a clearly understood short-term need; the best reason to pause is any uncertainty about what repayment will do to the rest of the month. I would recommend opening it only when I can review the details calmly, compare alternatives, and keep a personal record of the final decision. Used with that discipline, Money App - Cash Advance can be a practical place to explore an emergency-cash option. Used impulsively, its convenience may become the very thing that makes a difficult financial situation harder.
Overall, I would recommend it selectively rather than universally. It is a reasonable fit for a confident mobile user facing a one-off cash gap, but not my first choice for ongoing financial hardship, complex debt, or anyone who needs hands-on support. That balanced position is also the fairest way to judge Money App - Cash Advance: accessible enough to investigate, but important enough to approach slowly.
Pros
- Simple application process with minimal paperwork
- Fast eligibility checks for qualifying users
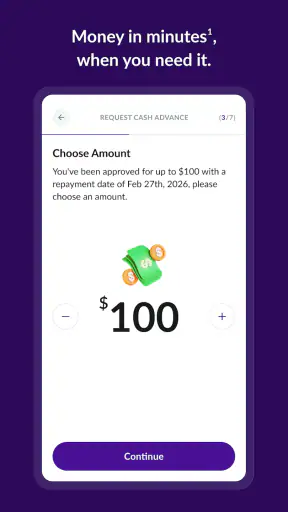
- Clear repayment schedule before accepting an advance
- Useful for covering unexpected short-term expenses
- Available balance and repayment details are easy to track
Cons
- Advance limits may be low for larger financial emergencies
- Fees or expedited transfer charges can reduce the amount received
- Repayment dates may be difficult to change after approval
- Eligibility and availability can vary by state or region
- Late repayment may lead to extra costs or affect future access
FAQs for Money App - Cash Advance
What is Money App – Cash Advance, and how does it work?
Money App – Cash Advance is designed to help eligible users access a small amount of money before their next payday. After creating an account, you typically provide personal, employment, and banking information so the service can assess eligibility. If approved, the advance may be transferred to a linked account, while repayment is generally scheduled for a later date. Availability and terms can vary by user and location.
How much money can I borrow through Money App – Cash Advance?
The amount available through Money App – Cash Advance depends on several factors, including your account activity, income information, repayment history, and the provider’s eligibility rules. New users may receive a lower limit, while consistent use could affect future offers. The app should display the exact advance amount, repayment date, fees, and any optional charges before you accept an offer, so review everything carefully.
Does Money App – Cash Advance charge fees or interest?
Cash advance services may use different pricing models, including subscription charges, express-transfer fees, optional tips, or other service costs. The total expense can depend on how quickly you want the money and which features you use. Before confirming an advance, examine the fee breakdown and repayment details inside the app. Do not assume that receiving money early is free, and compare the cost with other available options.
How quickly can I receive money, and what bank accounts are supported?
Delivery time depends on the verification process, your bank, weekends or holidays, and whether you choose a standard or expedited transfer. Standard deposits may take longer, while faster delivery can involve an additional fee. You will generally need to connect an eligible personal checking account in your name. Carefully verify account details, because incorrect information can delay the transfer or create repayment problems.
Is Money App – Cash Advance safe to use, and what should I consider before downloading it?
Before using the app, check its privacy policy, permissions, user agreement, and the identity of the financial service provider behind the product. You may be asked to share sensitive information, including banking and income details, so download only from an official app store and avoid unofficial copies. A cash advance is not a long-term financial solution; missing repayment can lead to fees, account restrictions, or financial stress.

Money App - Cash Advance
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@money.app, visit https://cash.money.app/, or review their https://cash.money.app/policies/Privacy-Policy-Money-App.html.










